
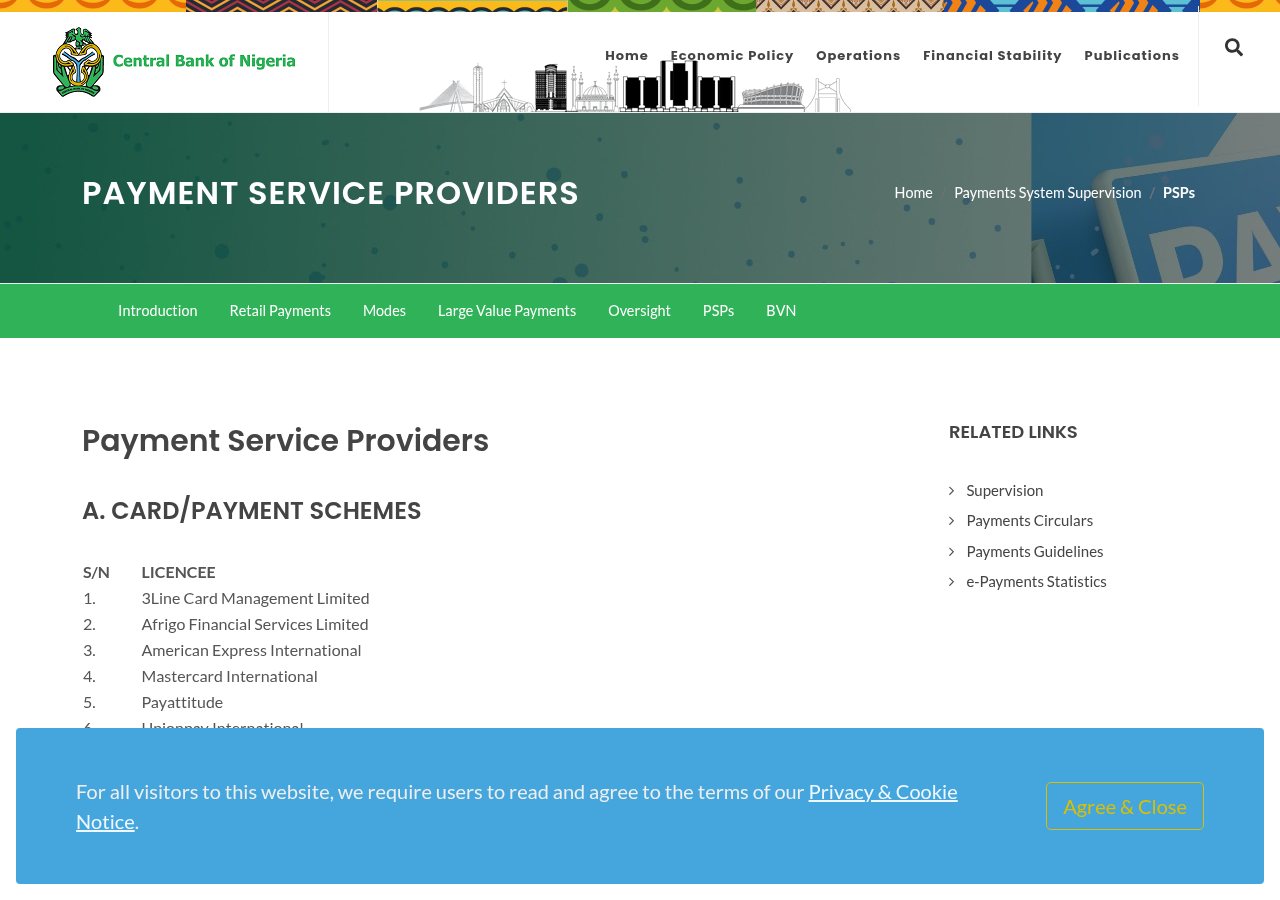
The CBN Payment Service Providers page listed Verve International in the card/payment schemes category.
| CBN category | Card/payment scheme |
|---|---|
| Listed institution | Verve International |
| Issuer relationship | The customer’s bank issues and controls the individual card/account |
| Checkout relationship | A gateway/acquirer transmits the merchant payment |
| Casino meaning | Acceptance is not licence, identity, fairness or payout evidence |
Questions this file answers
Primary intent: can I use a Verve card at a Nigeria casino and how do I dispute a failed debit safely
- Do Nigerian online casinos accept Verve cards?
- Does a Verve logo prove a casino is legitimate?
- Why was my Verve card debited without a casino credit?
- Who handles a Verve chargeback: bank, gateway or casino?
- Should I send casino support a photo of my Verve card?
- Can casino winnings be withdrawn back to a Verve card?
Captured evidence
These are locally stored captures of real public regulator, government or provider/operator material checked on 13 August 2026. Brand images are evidence records, not outgoing links or verdicts.
A Verve casino payment has at least four actors
Most failed-card complaints become clearer once the actors are named instead of calling all of them “Verve”.
| Actor | What it controls | What to ask for |
|---|---|---|
| Issuing bank | Card, account debit, authorisation and cardholder dispute | Final debit/reversal status and dispute reference |
| Verve scheme | Scheme rules and card-rail interoperability | Usually reached through the issuing bank rather than a casino chat |
| Gateway/acquirer | Checkout processing and merchant transaction reference | Gateway status and merchant descriptor where available |
| Casino operator | Gaming-account deposit credit and withdrawal approval | Deposit ID, account ledger and payout reference |
| State regulator | Gaming authorisation in its jurisdiction | Company, trade name, category, domain and dated period |
What the CBN list and Interswitch material establish
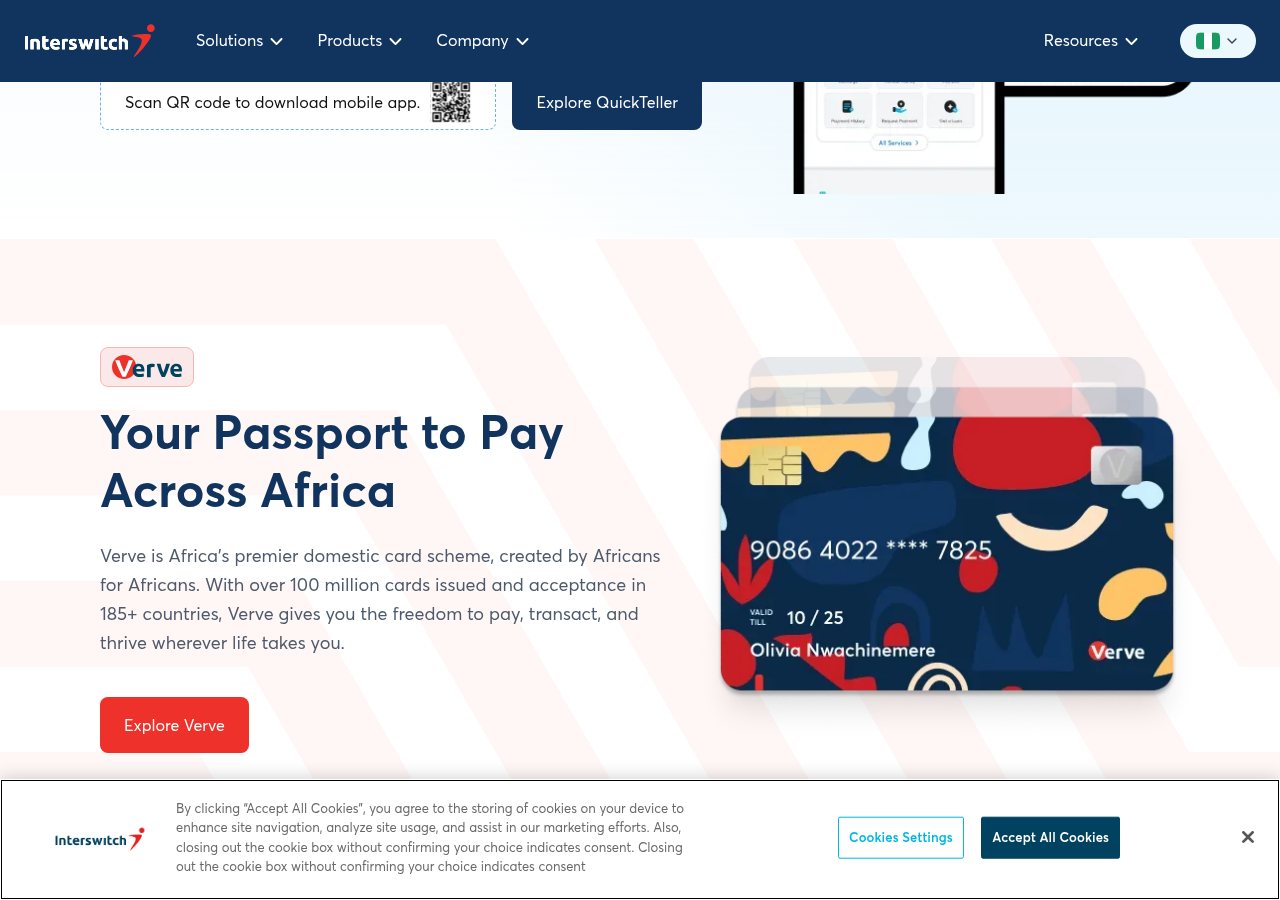
CBN lists Verve International among card/payment schemes. Interswitch’s brand material describes Verve as a domestic African card scheme, while its Quickteller support says Nigeria-issued Verve, Mastercard and Visa cards can be accepted in that environment. Those sources support the existence and local relevance of the rail. They do not tell us which casino cashiers currently enable it.
Card acceptance can vary by issuing bank, gateway, merchant configuration, risk controls and transaction type. A casino may show a Verve symbol yet decline a particular card, or may accept deposits but not return withdrawals through the same route. Check the live cashier before funding and read the operator’s return-of-funds rule.
Debited, no casino credit: the evidence order
Do not expose card credentials while trying to prove the debit.
- Checkout
Save the merchant context
Capture exact casino domain, account ID, amount, gateway, time and on-screen result.
- Bank
Confirm the debit
Keep the alert and statement entry with merchant descriptor and bank reference. An authorisation hold may differ from a posted debit.
- Casino
Search the deposit ledger
Give the safe reference and ask whether the transaction is successful, failed, pending or unmatched.
- Gateway
Obtain processing status
Where identified, use its support route with the transaction reference—not full card data.
- Issuer
Open a card dispute if appropriate
The issuing bank controls the cardholder dispute and will specify evidence and timing.
- Follow-up
Record reversal or credit
Check the statement, not only SMS alerts, and close duplicate cases with the final outcome.
Safe card evidence
A full card photograph can allow unauthorised card-not-present use. Verification evidence should be minimised and transmitted only through an authenticated route.
- Never send the card PIN, one-time password or complete security code. Those can authorise a transaction and are not complaint evidence.
- If an operator’s documented KYC process requests a card image, cover the CVV and all digits except the limited set it expressly requires. Confirm whether the issuer permits the request.
- A bank statement segment or debit alert can often prove the charge without exposing the full primary account number. Keep the merchant descriptor and reference visible.
- Do not upload card evidence through WhatsApp, Telegram, social direct message or an email reached only from an unsolicited message.
- If card details may be compromised, contact the issuing bank immediately to restrict or replace the card before pursuing the casino dispute.
- Use a unique casino password. Card data theft and credential reuse are separate risks that can occur on the same clone page.
Chargebacks are not a substitute for the operator complaint process
A cardholder dispute can address an unauthorised charge, duplicate debit, failed service or other issuer-defined reason. It does not decide a game result, bonus interpretation or whether an account breached casino terms. Give the bank accurate facts and the operator’s response. Do not describe an authorised deposit as unauthorised merely because a later withdrawal is disputed.
Operators may suspend an account while a chargeback is investigated, and scheme deadlines can be short. Raise the casino account complaint and bank card issue promptly, keeping their scopes separate. If the merchant resolves the credit or refund, tell the bank so the record does not continue on a false premise.
Withdrawing to a card is also operator- and gateway-specific. Some services return funds through the deposit route; others use bank transfer. A Verve deposit is not evidence that the same card supports payouts. Record the method offered in the logged-in withdrawal screen before assuming closed-loop capability.
Logo and clone checks
Verve artwork can be copied onto a fake cashier. The real test is the casino domain, legal company, secure checkout context, merchant descriptor and confirmation in the issuing bank’s own app. A browser padlock encrypts a connection but does not establish that the merchant is authorised or honest.
We checked public CBN and Interswitch material; we did not use a card, test a gateway, contact an issuer or file a chargeback. No anonymous report underpins the green status, which applies only to Verve International’s CBN card-scheme category.
Evidence ledger
Regulator and government citations may open their official source. Commercial material is listed without an outbound link; full provenance, capture hash and access metadata remain in the internal research ledger.
| ID | Source | Checked | Observation used | Role |
|---|---|---|---|---|
| VC-E1 | Payment service providers | 13 Aug 2026 | CBN listed Verve International in the card/payment scheme category | status |
| VC-E2 | Verve brand profile | 13 Aug 2026 | Interswitch described Verve as its domestic card scheme | provider identity |
| VC-E3 | Nigeria-issued cards accepted by Quickteller | 13 Aug 2026 | Support material described acceptance of Nigeria-issued Verve cards in Quickteller | acceptance context |
| VC-E4 | Fraud and scam awareness | 13 Aug 2026 | CBN guidance informed card credential and fraud-response controls | payment safety |
| VC-E5 | Complaints management | 13 Aug 2026 | CBN supplied the bank-first financial complaint route | complaint route |
| VC-E6 | Consumer complaint FAQ | 13 Aug 2026 | FCCPC supplied provider-first consumer complaint requirements | consumer route |
Conclusion: a real Nigerian card rail with multi-party disputes
Verve International was listed by CBN as a card/payment scheme. At a casino checkout, the issuing bank, scheme, gateway and merchant retain different records. Preserve the merchant descriptor and references, minimise card data, and send game-account issues to the operator while sending debit/charge disputes to the issuer. A Verve logo does not validate the casino or promise that withdrawals return to the card.
Continue the evidence trail
Nigeria payment catalogue · KYC guide · Complaint routes · Clone checks
Questions people ask
Do Nigerian casinos accept Verve cards?
Some cashiers and gateways may, but availability varies. Check the live authenticated cashier and issuing-bank controls before depositing.
Does a Verve logo prove the casino is legitimate?
No. It indicates a claimed payment option. Verify the casino company, state record, exact domain and checkout recipient separately.
Who handles a Verve debit with no casino credit?
Ask the casino to search its deposit reference and the issuing bank for final debit/reversal status. The gateway may also have a processing reference.
Should I send a full card photo for KYC?
No. Never reveal the CVV, PIN or OTP. If documented KYC requires a limited card image, verify the channel and mask all digits except those expressly requested.
Can I withdraw winnings to the same Verve card?
Do not assume so. The operator and gateway decide available payout routes; capture the logged-in withdrawal options and terms before funding.
Dated sources
All sources were checked on 13 August 2026. Government and regulator citations open only on their official domains. Provider and operator materials remain non-clickable public capture records.
- Payment service providersCentral Bank of Nigeria · Current CBN licence-category lists for schemes, mobile money, switching and processing · accessed 13 August 2026
- Verve brand profileInterswitch · Domestic card-scheme description and payment-channel context · accessed 13 August 2026
- Nigeria-issued cards accepted by QuicktellerInterswitch Self Service · Verve, Mastercard and Visa support statement · accessed 13 August 2026
- Fraud and scam awarenessCentral Bank of Nigeria · Payment credential and fraud-response guidance · accessed 13 August 2026
- Complaints managementCentral Bank of Nigeria · Bank-first complaint handling and escalation guidance · accessed 13 August 2026
- Consumer complaint FAQFederal Competition and Consumer Protection Commission · Provider-first complaint steps, evidence and FCCPC escalation · accessed 13 August 2026